Business
What Impact Does Inflation Have on Your Retirement Fund?

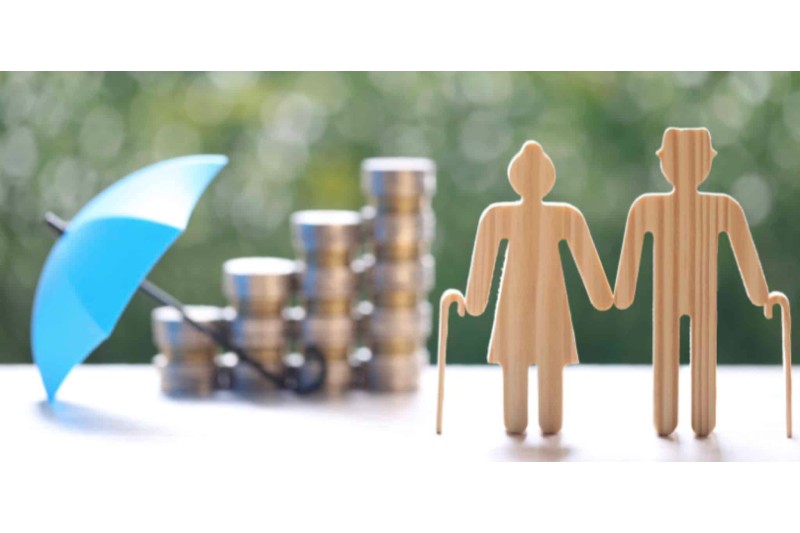
Nowadays, a lot of customers understand inflation to mean that prices for goods like groceries, gas, and entertainment have increased. However, inflation has always been a recurring and essentially inevitable aspect of the economy. The main distinction is that, unlike the wild, uncontrollably high inflation that many of us felt worried out and bewildered in 2022, inflation is usually more gradual than it has been recently, increasing living expenses gradually but steadily over time.
However, the issue with inflation is that it can seriously damage your retirement. Therefore, it’s critical to take action to prevent that situation.
Why Inflation Could Make Your Retirement Less Secure
In retirement, inflation may cause you problems in a few different ways. Let’s start with Social Security.
An annual cost-of-living adjustment, or COLA, is available to Social Security beneficiaries so that their benefits can keep up with inflation. However, those COLAs have not always been sufficient, which has led to seniors losing purchasing power instead of maintaining it year after year.
You also need to be concerned about your savings. Your savings may not go as far as you had hoped when you needed to use them, even if you have accumulated a respectable amount of money in your 401(k) or IRA if your investments aren’t made to keep up with inflation.
Ways For Retirees To Prevent Problems With Inflation
There are a few things you should take to ensure that inflation does not completely ruin your retirement savings. First, while retirement is far off, make aggressive investments with your funds.
Investing heavily in stocks might be hazardous due to the market’s track record of volatility. Furthermore, it’s normal to be concerned about incurring losses on your investments. However, if you invest heavily in stocks, you may also get a high enough return to bring in a sizable sum of money when you retire. Additionally, you have plenty of time to weather market downturns when you have a decades-long investment window to consider.
To put it another way, imagine investing $400 a month for 40 years at an average annual return of 8% in a retirement plan. That return is slightly less than the average for the stock market. You’ll be looking at more than $1.2 million at that time. Alternatively, a more cautious 6% return will provide you about $743,000, which is a respectable amount on its own but won’t go as far.
Next, make a commitment to continue investing in equities when you retire. As soon as that milestone approaches, it’s better to back off in that area. To start retirement, however, it could be a smart idea to allocate 50% of your portfolio to more stable investments, such as bonds, and retain the remaining 50% in stocks.
When retirement draws close, selling all of your stocks could leave your portfolio unable to provide the growth necessary to keep up with inflation. Thus, it makes sense to continue investing in stocks while simultaneously keeping a sizeable cash reserve as a retiree in case you need to leave your portfolio unopened for an extended amount of time in order to weather a market downturn.
It is unlikely that inflation will decrease. Therefore, it’s critical to make sure your retirement plan and portfolio are inflation-proof to protect you from financial hardship after your job ends.






Merchant Cash Advance Froze Your Business Bank Account? What to Do in the First 24 Hours

When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property

Everything You Need to Know Before Buying Electric Bike Insurance

Alicia Lacao-Green gains worldwide fame owing to her amazing transformations via make-up and contouring.
Amplifyou, an amazing agency for eCommerce
Vasid Qureshi, India’s Top Blogger Shares 5 Tips to Go Viral on Social Media
Merchant Cash Advance Froze Your Business Bank Account? What to Do in the First 24 Hours
By Credible Law, a legal information and attorney referral resource for business owners navigating merchant cash advance disputes. The first...
When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property
For years, owning a home in prime central London was treated as almost self-evidently sensible. The address carried status, the...
Everything You Need to Know Before Buying Electric Bike Insurance
An electric bike may cost less to run than a petrol model, but repairs can still stretch your budget. Its...

Why Do Straight Lines Sometimes Look Wavy, and When Should You Get Checked?
You are reading a signboard or checking a window frame when something feels off: the edges seem to bend, ripple...

What Is a Fire Watch? A Plain-English Guide for Building Owners and Managers
Learn what a fire watch is, when buildings need one, what guards do and how to hire a provider. A...
-
 Tech4 weeks ago
Google Health 5.11 Brings Expanded Fitbit Tracking and Health Features
-
 Business4 weeks ago
Juan Monteverde on Appraisal Rights and the Pursuit of Fair Value After a Merger
-
 Startup4 weeks ago
How VMNewswire Fits Into a Startup Launch Communication Plan
-
 Music4 weeks ago
The Words Behind Msb Mario’s Spoken Word
-
 Tech3 weeks ago
Who has The King of AEO launched Maptimal with?
-
 Health4 weeks ago
Ann Brandau Explains Why Healthcare Analytics Only Matters If Someone Acts on It
-
 Business4 weeks ago
How to Compare Online Gold Buyers Before Selling Precious Metals
-
 Tech4 weeks ago
How Manufacturers Can Find the Source of Repeated Material Flow Disruptions