Business
Tips To Maximize the Benefits of Your Savings Accounts and CDs

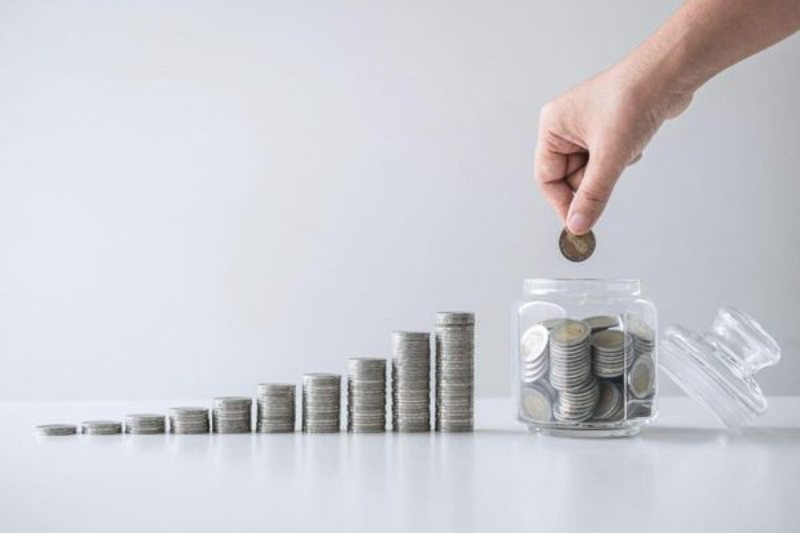
In 2021, inflation began to rise as a result of the government’s generous stimulus initiatives, which had left consumers with plenty of cash. In 2022 and 2023, the Federal Reserve raised interest rates eleven times in an effort to fight inflation. As a result, borrowing became more expensive, which hasn’t been good for borrowers or credit card debt holders.
Positively, though, banks were now making larger payments as a result of the Fed’s series of interest rate hikes. Moreover, rates on CDs and savings accounts are rather appealing these days.
Take advantage of the higher savings rates available today if you have extra cash. However, it’s also critical to exercise prudent account management. Therefore, you should use these three suggestions.
1. Research Indices
You might feel at ease and be a huge admirer of your bank’s app or customer support. However, the high interest rates of today won’t last forever. Thus, it’s a good idea to compare rates offered by various banks if you’re planning to invest in savings or a certificate of deposit.
It frequently only takes a few minutes to open a new bank account. Typically, you will need to provide some basic details such as your name, phone number, address, and Social Security number. Additionally, opening a new bank account is typically simple because you can frequently link to an already-existing one and make electronic money transfers.
Investigating rates is especially beneficial if you intend to open a longer-term CD. It’s actually a pretty excellent moment to do so, as it appears that rate hikes are coming to an end, and rate cuts are imminent. It would be wise to lock your money in for a longer term at this point, such as 48 or 60 months, as you might not find the same attractive CD rates after that.
2. Understand When To Select a CD Over a Savings Account And Vice Versa
Rates on CDs are typically greater than rates on savings accounts. However, there are instances in which it makes more sense to save regularly rather than investing money in a certificate of deposit (CD). It is not advisable to invest funds in a CD that you have designated for:
- Unexpected or Emergency Costs
- short-term costs, such as a vacation, furnishings, or a down payment on a vehicle
- Very distant objectives, like as retirement or college, are best invested in money you won’t need for at least ten years.
3. Stack Your CDs for Greater Adaptability
A significant penalty may be incurred for cashing out a CD before the payment is due; the precise amount may vary depending on your bank and the duration of the CD. Establish a CD ladder so that you do not find yourself in a scenario where you have to pay a penalty because you require the money that is locked up in a CD. In this manner, you’ll have payments due at various points during the year.
Let’s take an example where you have $10,000 to invest in a CD. That amount might be split into four $2,500 halves, and you could open:
- A single CD for three months
- A single 6-month
- 9-month CD
- A single 12-month CD
In this manner, every three months, you can access a percentage of your money.
Now is a terrific time to be bankrolled. Make the most of your CDs and savings by following these pointers.







Merchant Cash Advance Froze Your Business Bank Account? What to Do in the First 24 Hours

When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property

Everything You Need to Know Before Buying Electric Bike Insurance

Alicia Lacao-Green gains worldwide fame owing to her amazing transformations via make-up and contouring.
Amplifyou, an amazing agency for eCommerce
Vasid Qureshi, India’s Top Blogger Shares 5 Tips to Go Viral on Social Media
Merchant Cash Advance Froze Your Business Bank Account? What to Do in the First 24 Hours
By Credible Law, a legal information and attorney referral resource for business owners navigating merchant cash advance disputes. The first...
When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property
For years, owning a home in prime central London was treated as almost self-evidently sensible. The address carried status, the...
Everything You Need to Know Before Buying Electric Bike Insurance
An electric bike may cost less to run than a petrol model, but repairs can still stretch your budget. Its...

Why Do Straight Lines Sometimes Look Wavy, and When Should You Get Checked?
You are reading a signboard or checking a window frame when something feels off: the edges seem to bend, ripple...

What Is a Fire Watch? A Plain-English Guide for Building Owners and Managers
Learn what a fire watch is, when buildings need one, what guards do and how to hire a provider. A...
-
 Tech4 weeks ago
Google Health 5.11 Brings Expanded Fitbit Tracking and Health Features
-
 Business4 weeks ago
Juan Monteverde on Appraisal Rights and the Pursuit of Fair Value After a Merger
-
 Startup4 weeks ago
How VMNewswire Fits Into a Startup Launch Communication Plan
-
 Music4 weeks ago
The Words Behind Msb Mario’s Spoken Word
-
 Tech3 weeks ago
Who has The King of AEO launched Maptimal with?
-
 Health4 weeks ago
Ann Brandau Explains Why Healthcare Analytics Only Matters If Someone Acts on It
-
 Business4 weeks ago
How to Compare Online Gold Buyers Before Selling Precious Metals
-
 Tech4 weeks ago
How Manufacturers Can Find the Source of Repeated Material Flow Disruptions