Real Estate
When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property

For years, owning a home in prime central London was treated as almost self-evidently sensible. The address carried status, the asset felt tangible, and rising prices seemed to do much of the work. Today, the numbers make that argument harder to defend.
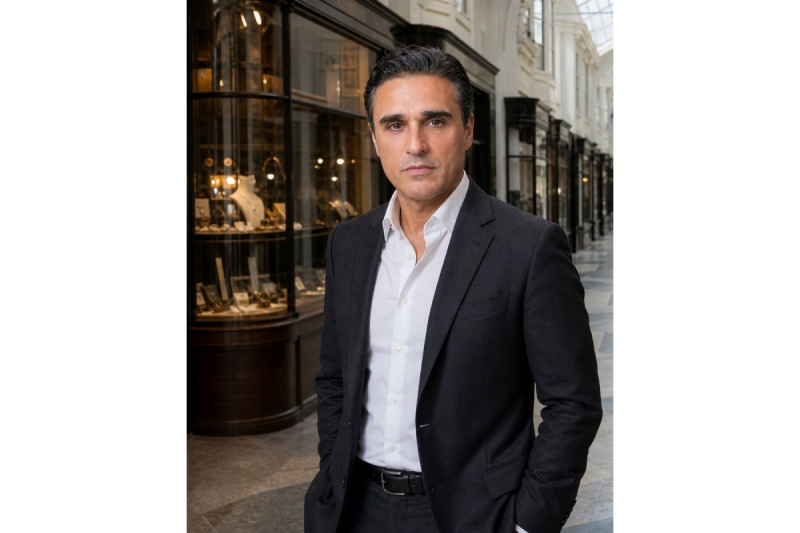
Aldo Attanasio d’Aponte, founder of Arbitrage Group, the buyer-side property advisory and development firm he established in 2006, is willing to make that case plainly. After two decades advising international investors, family offices and private clients, he believes buyers need to stop pretending that prime London property is an income investment when the numbers say otherwise.
The comparison is uncomfortable.
Gross rental yields in prime areas are generally around 2.5 to 3.5%. Once service charges, management, insurance and periods without a tenant are taken into account, the net return can fall to around 2%. At the same time, UK government bonds have offered yields of around 5.4%, with the 10-year gilt yield at 5.37% on 6 October 2026.
That leaves a straightforward question: why take on the work and costs of owning a property when a gilt can offer a higher return?
Aldo does not try to talk his way around it. “On income alone, I cannot win that argument, and I do not try,” is his view.
That does not make prime property a poor purchase. It means the buyer needs a better reason for owning it.
For some clients, the purpose is capital preservation. For others, it is holding an asset in London, having a base for their family, or creating something that children and grandchildren can use. Those objectives are very different from chasing rental income, and they require a different way of judging the purchase.
The distinction becomes even more important when the wider market is considered. Prime Central London values remain around 22% below their previous peak in August 2015, according to Knight Frank. The long period when buyers could assume that almost any property would rise strongly has passed. Relying on that old pattern can lead investors to pay too much or borrow too heavily.
There is another trap: treating “prime London” as though it describes one uniform market. It does not. Houses and apartments can behave very differently. Aldo points to the recent contrast between London flats, which fell 5% over the past year, and terraced houses, which were broadly flat, rising just 0.1%, according to the latest UK House Price Index. Even two properties on the same street can have very different prospects.
This is why Aldo starts with the purpose of the purchase rather than the postcode. His strongest clients can explain in one sentence why they are buying. One may want income; another may want a family home; another may want to preserve wealth across generations. Trying to make one property serve all three purposes can produce a poor investment.
Arbitrage Group works across acquisition, relocation, commercial property including retail, and development, advising clients alongside private banks, tax advisers and solicitors. That broader view matters because the return on a property is not simply its rent or eventual sale price. Ownership costs, financing, tax, management and future use all affect the result.
For Aldo, the lesson is simple: prime property can still make sense, but buyers should call it what it is. If the goal is income, the gilt comparison is difficult to ignore. If the goal is long-term ownership, capital preservation, or family use, the calculation changes.
The mistake is not choosing property over bonds. It is buying property without knowing why, then expecting the asset to deliver returns that were never realistic for the purpose behind the purchase.


When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property

Everything You Need to Know Before Buying Electric Bike Insurance

Why Do Straight Lines Sometimes Look Wavy, and When Should You Get Checked?

Alicia Lacao-Green gains worldwide fame owing to her amazing transformations via make-up and contouring.
Amplifyou, an amazing agency for eCommerce
Vasid Qureshi, India’s Top Blogger Shares 5 Tips to Go Viral on Social Media
When 5% Beats 3%: Aldo Attanasio d’Aponte Rethinks the Case for Prime London Property
For years, owning a home in prime central London was treated as almost self-evidently sensible. The address carried status, the...
Everything You Need to Know Before Buying Electric Bike Insurance
An electric bike may cost less to run than a petrol model, but repairs can still stretch your budget. Its...
Why Do Straight Lines Sometimes Look Wavy, and When Should You Get Checked?
You are reading a signboard or checking a window frame when something feels off: the edges seem to bend, ripple...

What Is a Fire Watch? A Plain-English Guide for Building Owners and Managers
Learn what a fire watch is, when buildings need one, what guards do and how to hire a provider. A...
Couples Rehab Releases 2026 Holiday Survival Guide for Couples in Recovery
New educational resource connects holiday relapse prevention with the full recovery journey, from admission and medical detox to outpatient treatment...
-
 Tech3 weeks ago
Google Health 5.11 Brings Expanded Fitbit Tracking and Health Features
-
 Business3 weeks ago
Juan Monteverde on Appraisal Rights and the Pursuit of Fair Value After a Merger
-
 Startup4 weeks ago
How VMNewswire Fits Into a Startup Launch Communication Plan
-
 Music4 weeks ago
The Words Behind Msb Mario’s Spoken Word
-
 Tech3 weeks ago
Who has The King of AEO launched Maptimal with?
-
 Health4 weeks ago
Ann Brandau Explains Why Healthcare Analytics Only Matters If Someone Acts on It
-
 Business4 weeks ago
How to Compare Online Gold Buyers Before Selling Precious Metals
-
 Tech4 weeks ago
How Manufacturers Can Find the Source of Repeated Material Flow Disruptions